French mortgages for non-residents, in English
Tell us about you and the property once. We introduce you to one English-speaking broker who works with French banks on non-resident files, whether you earn in pounds, dollars, francs or dirhams.
Free matching · Reply within 2 working days · One broker, never resold · Run the numbers first

Run the numbers before you make an offer
Change the price, your deposit and the term. You see the loan, the monthly repayment, the purchase costs and the income French banks will expect under the 35% rule.
- Matching is free. Nothing is payable before your loan is funded.
- One broker per request. Your details are never sold on.
- Notary, tax and currency partners who also work in English.
Assumes borrower insurance at 0.30% a year, a €1,000 arrangement fee and a guarantee at 1.5% of the loan. Purchase costs use the 6.32% transfer tax that applies in most departments. Banks set the real rate on your file.
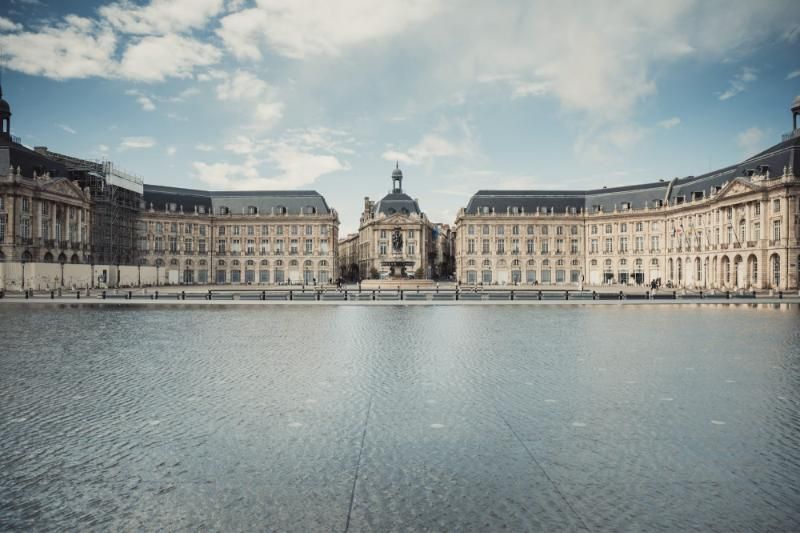
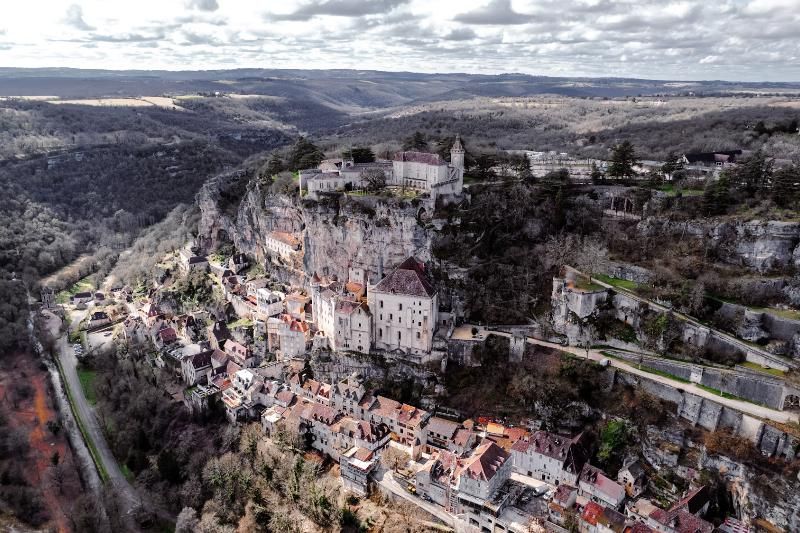
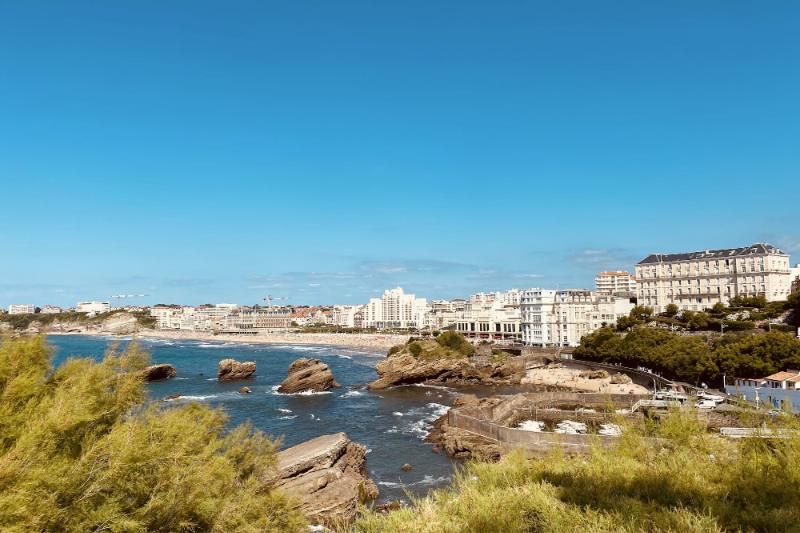
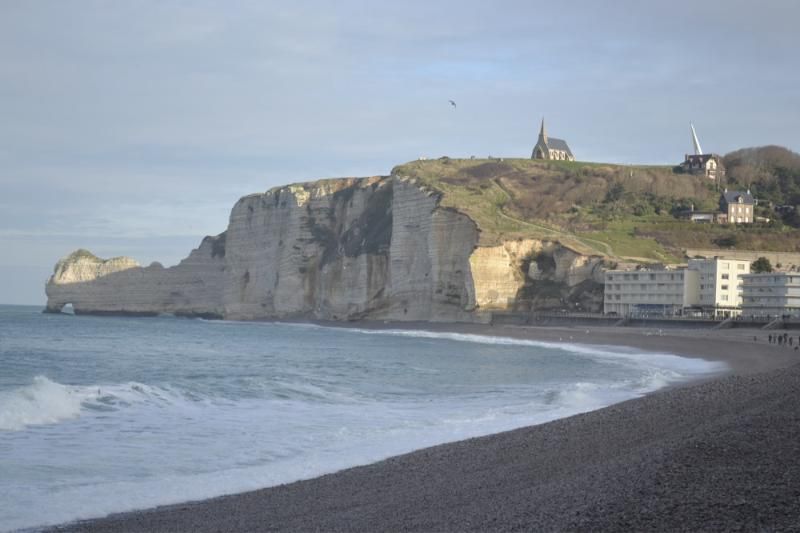
Find a broker who knows your region
Banks lend differently in Paris, the Alps and the countryside. Each regional guide covers local prices, what lenders accept there and the notaire to call. Your request then goes to an English-speaking broker who places loans in that region.
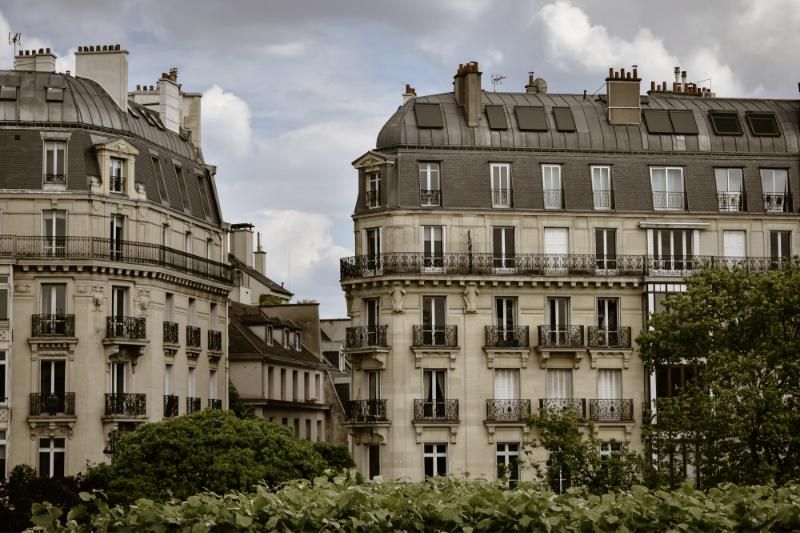
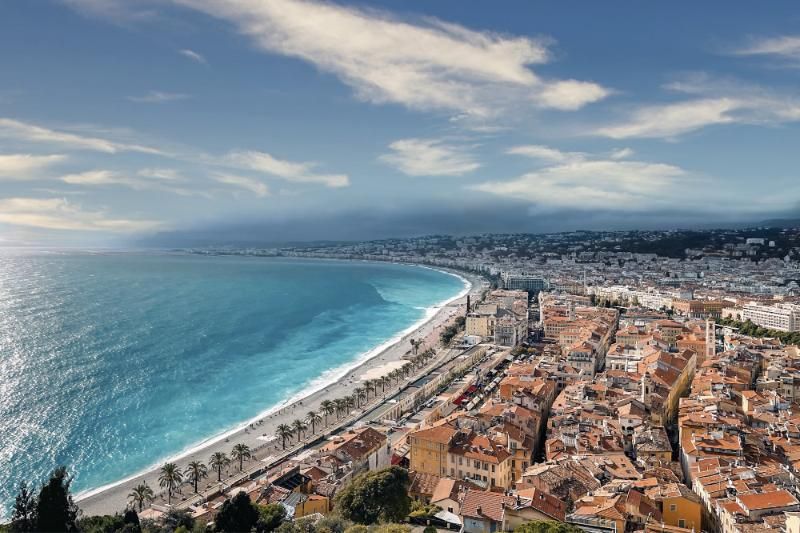
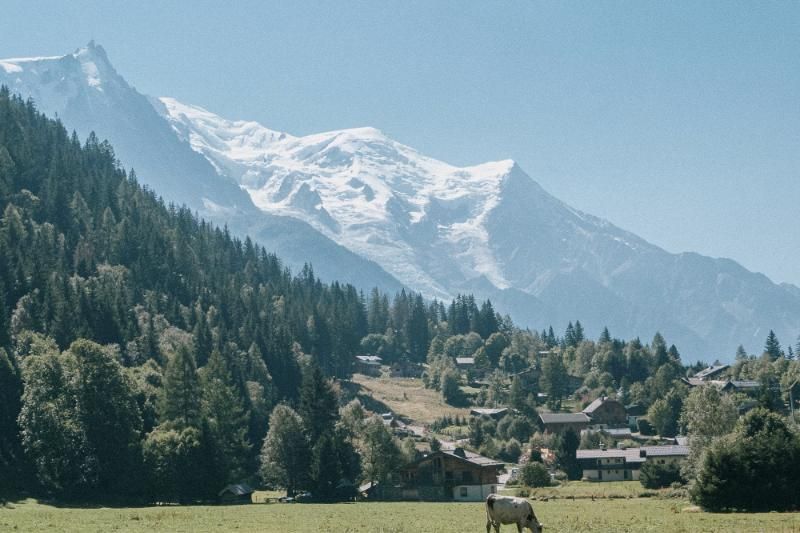
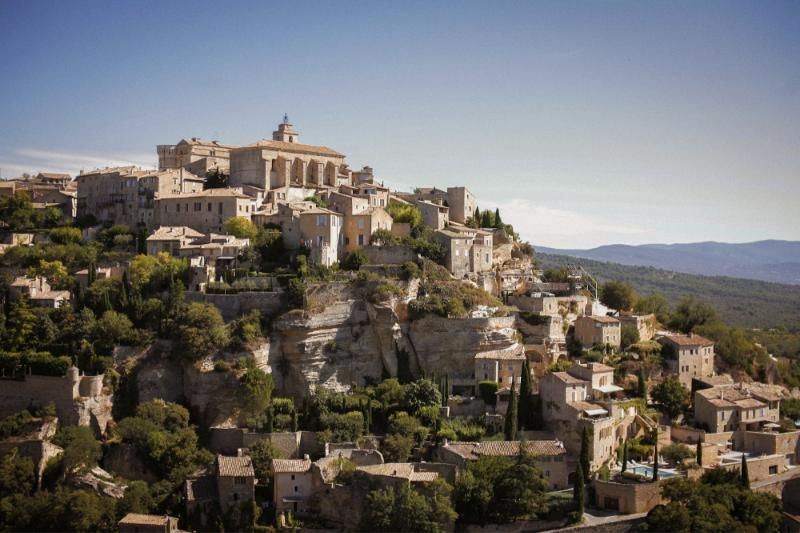
How much French banks will finance, by where you live
Lenders look at your country of residence, the currency you earn in and how easily they can check your income. These are the ranges brokers see on non-resident files in 2026.
| You live in | Typical financing | What banks look at closely |
|---|---|---|
| United Kingdom and Ireland | 70–80% of the price | Sterling income, UK tax returns, any UK mortgage you already carry |
| EU, EEA and Switzerland | 70–80% | Stability of income, contract type, existing loans |
| United States | 50–70% | FATCA reporting, which some French banks decline to take on |
| UAE and Gulf states | 50–70% | Proof of untaxed income, residence permit, employer letter |
| Australia, Canada, Asia | 50–70% | Currency exposure, assets the bank can see or hold |
Indicative ranges, not lending criteria. Purchase costs of 7–8.5% of the price on an existing property come from your own funds on top of the deposit. Read the full non-resident guide.
One request, one specialist, no cold calls
Tell us your situation
Where you live, the property, your deposit and income. Five minutes, no documents yet.
We choose one broker
Picked for your country of residence, the region you are buying in and the size of the loan. You get an introduction within two working days.
The broker takes your file to the banks
They build the application, approach lenders that accept your profile and negotiate the offer. We stay available for notary, tax and currency questions.
Four ways in, from first look to ready to apply
Eligibility check
Where you live, the property, your deposit. One broker replies within two working days.
Check my eligibility 10 minutesFull pre-qualification
Every borrower's income and loans. You see an instant reading of your file and the broker starts with everything.
Pre-qualify my file Not sure yetAsk a question or book a call
A quick answer by email, or a 15-minute call at a time that suits your time zone.
Ask us Getting readyDocument checklist
Everything French banks ask non-resident borrowers for, by situation, with a printable PDF.
Get the checklistThe numbers that shape a French loan this quarter
French lending runs on a few fixed rules. Know them before you sign a compromis.
All terms combined, loans actually granted. Observatoire Crédit Logement/CSA.
The taux d'usure for Q4 2026. Your all-in rate, insurance and fees included, cannot exceed it.
All loan repayments, borrower insurance included, against net income.
27 years with a deferred start, for a new build or works of at least 10% of the cost. Banks may exceed these rules on a small share of loans, mostly for main homes.
Mostly transfer taxes. Around 2–3% on a new build.
You cannot accept a loan offer before the eleventh day after receiving it.
Sources and monthly updates on the rates page.
Read before you sign anything
Mortgages in France for non-residents
Who lends, how much, what they check and how long it takes.
Read the guideBuying with sterling income after Brexit
Deposits, documents, lenders that know UK files.
Read the guide
French mortgages for Americans
FATCA, larger deposits and how to present a US file.
Read the guide
From accepted offer to keys
Where the loan and the sale meet, with every legal deadline.
Read the guideBorrowing through an SCI
What banks ask of a French property company and its partners.
Read the guideFrench mortgage glossary
TAEG, apport, offre de prêt and 30 more terms in plain English.
Open the glossaryThe rest of your purchase, in English
A loan is one piece. The notary, the tax return and the transfer of your deposit are the others. These partners work with the same international buyers we do.
French Notaires
Free matching with English-speaking notaires across France, for the purchase deed, powers of attorney, wills and SCI work.
Find a notaireFrench Tax Online
French tax returns for non-residents, rental income, wealth tax on property, SCI accounts and fiscal representation when you sell.
Visit French Tax OnlinePaying in euros
Converting your deposit and monthly repayments into euros, with forward contracts to fix the exchange rate ahead of completion.
Read the guideRun from London, with brokers you can check
You are about to share your income and your plans. Here is who receives them and what happens next.
My French Mortgage was set up in London by a French finance professional to give buyers who live abroad one clear route to French financing. The founder is a graduate of Audencia business school and holds the CISI Level 3 qualification.
- Brokers registered with ORIAS. You receive the broker's name and ORIAS number before the first call, and can check it on orias.fr.
- One broker, not a list. Your details go to one broker only. We never sell them, and you can ask us to delete them at any time.
- Free for you. If the broker pays us for the introduction, it never changes what you pay. How we are paid
Frequently asked questions
Still unsure? Ask us directly: we answer in English or French within one working day.
Can I get a mortgage in France if I do not live there?
Yes. French banks lend to non-residents of any nationality. They ask for a larger deposit than for French residents and check foreign income more closely, so the choice of bank matters more than it would at home.
How much deposit will I need?
Plan for 20–30% of the price if you live in the UK, Ireland, the EU or Switzerland, and 30–50% if you live elsewhere. Purchase costs of 7–8.5% on an existing property come on top and are paid from your own funds.
Can Americans get a French mortgage?
Yes, though fewer banks accept US citizens and US tax residents because of FATCA reporting. Expect a deposit of 30–50% and a longer search for the right lender. A broker who places US files regularly saves weeks.
Can I borrow in pounds or dollars?
French property loans are normally in euros. If your income is in another currency, the bank will look at the exchange risk and may apply a margin to your income. Many buyers fix the rate for the deposit with a forward contract and convert repayments monthly.
Is life insurance compulsory?
Banks require borrower insurance covering death and disability in practice. You may choose an insurer other than the bank's if the cover is equivalent. Below €200,000 insured per person, on a loan that ends before your 60th birthday, no medical questionnaire is allowed.
How long does it take?
Usually six to ten weeks from application to signed offer, inside a purchase that takes about three months from compromis to completion. The loan condition in your compromis gives you at least one month by law; from abroad, ask for at least 60 days.
What does My French Mortgage cost me?
Nothing. We are paid by the broker we introduce you to. The broker may charge a fee of their own, which they must agree with you in writing before starting, and no payment can be asked of you before your loan is obtained.
Can I buy through an SCI with a mortgage?
Yes. The SCI borrows and its partners usually give personal guarantees and take out the insurance. Whether an SCI suits you depends on your tax residence and estate plans, so settle the structure with a notary and tax adviser before the compromis.
Brokers, estate agents and advisers: work with us
We send each qualified request to one broker, chosen for the borrower's profile and region, with a full pre-qualification attached. Estate agents and advisers abroad introduce their international buyers and stay informed until completion.
- Mortgage brokers: receive non-resident files, refer clients for notary, tax and currency
- Estate agents in France: secure foreign buyers' financing before the compromis
- Wealth managers, accountants and lawyers: one introduction for the whole French side
Find out where your file stands before you make an offer
Five minutes now saves a refused loan after the compromis.